Economists turn out to be as stupid as journalists are lazy
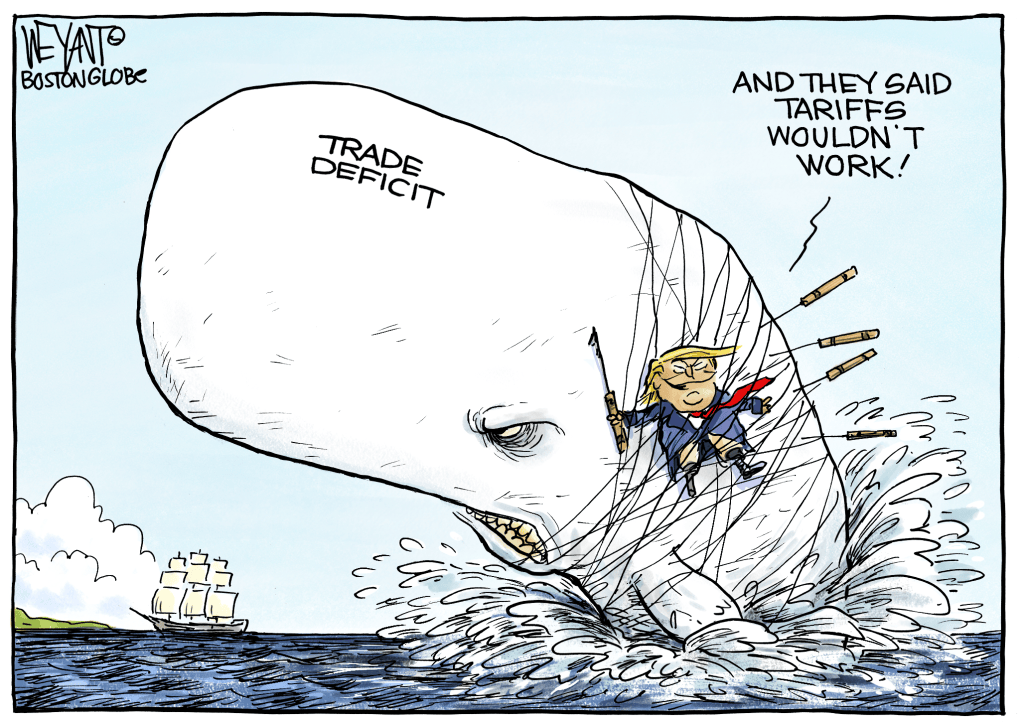
“It will never work anyway!”, comes the common refrain thrown at almost all disruption attempts in the last decade in response to the broadly technocratic and deterministic policies of the last half a century since the oil shock. Trump’s implementation of trade tariffs is a prime example of this. Critics of the policy broadly fell into two buckets. On the one hand, were those who predicted major and immediate crises of various sorts – an economic slump in the US, an inflation crisis, a currency collapse, an escalating trade war with no winners and no end. On the other hand, smug ‘super administrators’ focused with glee on the idea that the policy would never even achieve its stated objective of cutting the much discussed trade deficit.
The Cassandra-like forecasts of the first bucket would appear somewhat challenging after the fact. In the year since tariffs were implemented seriously, the US economy has been robust and by far the standout performer among OECD economies, while continuing to attract more outside investment than China or India (and by the way, the stock market is not doing poorly either). Inflation has stabilized from its Biden-era highs, and even the Fed agrees that tariffs have added at most 0.2%-0.4% to prices – never ideal but hardly the stuff of calamity. In the meantime, there has been no ‘trade war’, with the universal 10% levy imposed with almost no resistance and in the singular matter of China, as I have written about previously, the US has managed to achieve a positive tariff differential for the first time since the 1990s, and China has had to suck it up.
But it is the second charge – that the trade deficit cannot be brought down – that is currently doing the rounds. Journalists in particular react to monthly numbers a bit like football fans judge their manager by their last result. Economists are even worse, driven by a form of theoretical blindness. However it has now been a year since tariffs were brought in, and well worth examining what has occurred as a whole.
Notional trade deficit over last 15 years (monthly vs 12 month rolling average)
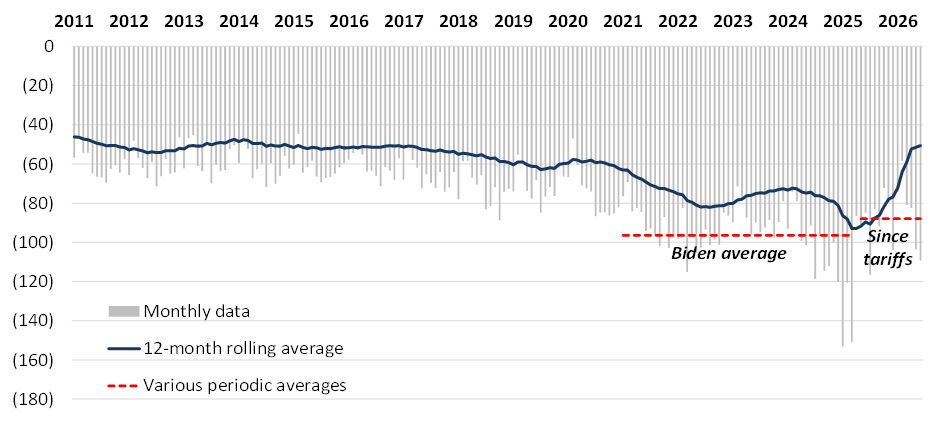
Even taking the critics at face value, using unadjusted monthly numbers, the deficit has fallen from an average of US$96bn per month in the four and a half years from Biden through to Liberation Day, to an average of US$88bn per month since, almost a -10% reduction. Using a simple mathematical concept like a rolling 12-month average (as shown above and something beyond the ken of most reporters, it seems) highlights this direction much more clearly. So far, so simple: the deficit is down and falling.
However this is not the end of the story. When assessing the impact of the tariffs on the trade deficit, the focus should really be on the industries being protected, rather than the whole economy, for obvious reasons. Major exemptions were instituted for strategic necessity – tariffs were not implemented clumsily and without thought. In particular, in the last few years we have entered a once-in-a-generation industrialization race regarding AI, which has led to huge distortions in the trade imbalance. Over the same period as above, imports under Harmonized Tariff Schedule (HTS) codes for semiconductor products (key categories 8541, 8542, 8471, 8473 and 8517) have jumped enormously and on purpose as America seeks to get ahead of the game in data centres and compute power.
Semiconductor (aka AI spend) as % of total trade deficit
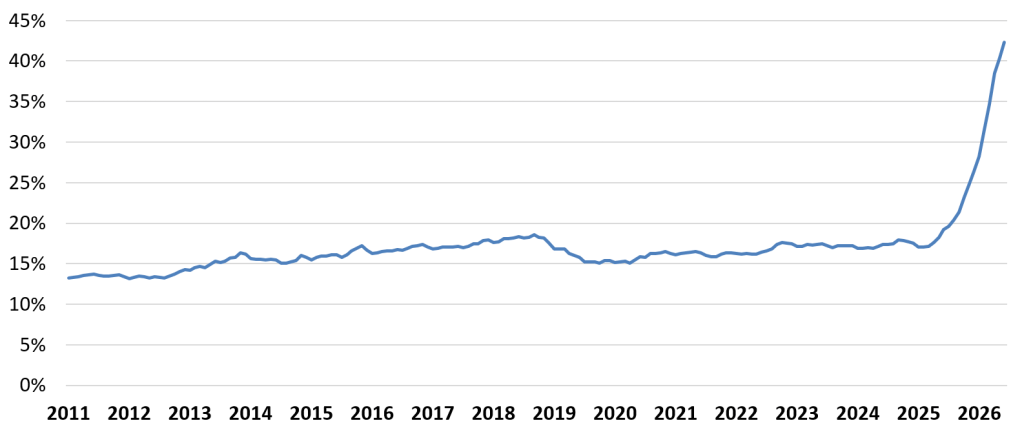
This has little to do with the aims and objectives of the so-called ‘trade war’, and does not take away from Rust Belt jobs. The success of tariffs from even the narrow perspective of the trade deficit, can only be understood through its impact on the industries being targeted, or their substitutes. On an intuitive basis (and despite what economists love to think) the importer of, say, cars is not going to substitute their purchasing power into less taxed segments such as semiconductors – there is no fungibility of capital occurring across unrelated segments. So there is a distinction to be made between the ‘core deficit’ and the exempted items, making the effects of tariffs even clearer.
US trade deficit over last 15 years (12 month rolling average)
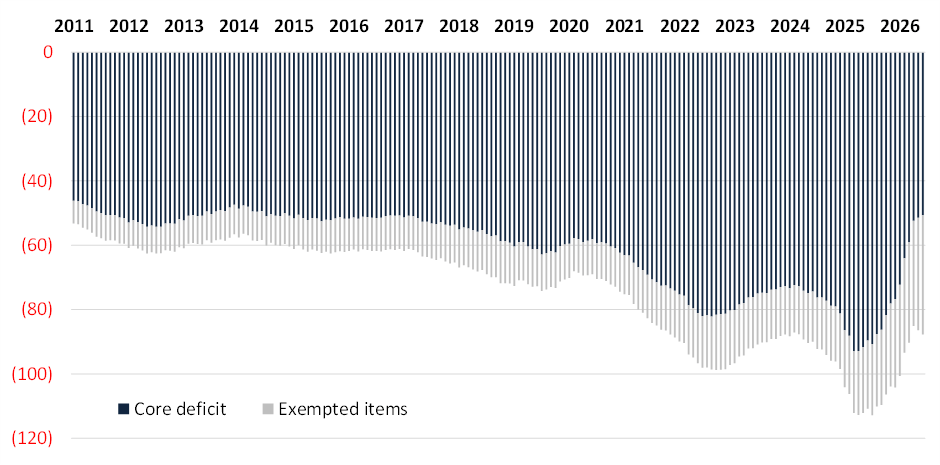
On a nominal basis, the trade deficit in the truly relevant industries has actually declined precipitously to levels not seen since the Obama administration. It has been reduced by more than a third from the highs of the Biden era – indeed the average ‘core deficit’ since Liberation Day is -13.4% lower than the entire 15 years preceding it. It has fallen to record lows as a result of tariffs.
Yet even this is not the whole story. In today’s money, the current total deficit is $88bn, while the ‘core deficit’ number stands at $51bn. You may choose to look at whichever number you like, but one must also factor in the time value of money. The US$88bn total deficit was last this low in Q4 2021, but US$88bn today is not the same as US$88bn five years ago. Likewise the last time the ‘core deficit’ was this low was way back in Q1 2017, a totally different world. The key metric to measure against is GDP of the day, basically allowing deficits to be benchmarked against a form of ‘inflation’. When examined in this light, the true and remarkable scale of the deficit reduction becomes apparent.
US trade deficit over last 15 years as % of GDP
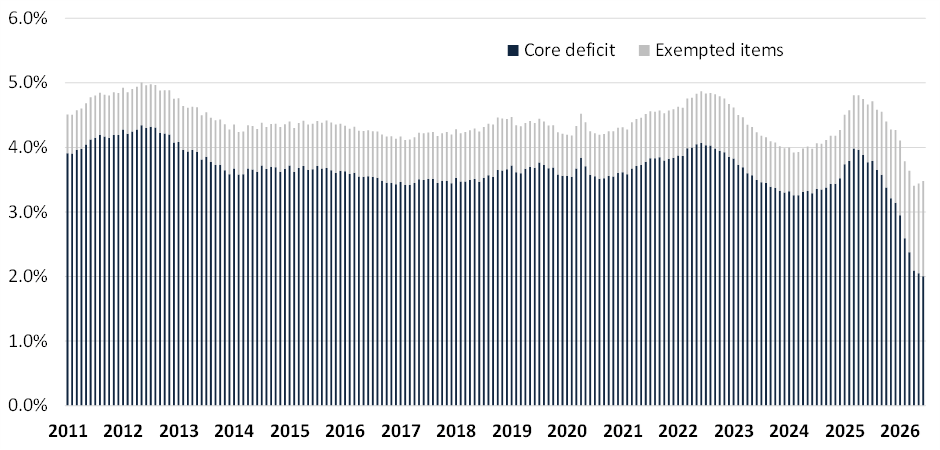
In short, the US trade deficit has fallen to levels not seen for decades – exactly as would be foretold if analysts did not keep needing to overthink it. And it has fallen against a backdrop of a strengthening economy which is seemingly more strongly positioned against its competitors than ever, a fact underlined by FDI being maintained at by far and away No 1 (with the US at US$277bn in 2025), a far cry from the 2000s and 2010s when China led on this metric.
There is plenty to dissect in this, and these statistics do not in themselves prove that tariffs are good for the economy, or even that reshoring is happening. Nonetheless there are only a few explanations as to why GDP can continue to grow even as the deficit reduces, and the likelihood is that these reasons are ‘good growth’. A major component of it has been the US ability to increase productivity and replace imports effectively, most of which helps with job growth – another area which has “surprised” economists on the upside. While there are other potential reasons – currency effects and exogenous slowdown – these will not account for the bulk of what is happening.
Ultimately the debate over tariffs should always have been a long-term one, over whether free trade or whether selective trade benefits an economy and a society more. The scaremongering over near-term effects is always counterproductive to the critique and often wrong, as has been demonstrated here. Above all though, critics need to learn what I first noted a decade ago: that trying to tell people that changes “will not work” makes them increasingly angry over the lack of agency politicians represent. Argue that it is bad, by all means, but there is no point implying that the great system of global economy and relations makes independent national policies redundant. Nobody is here to listen to that and even bad independence will be rewarded over good dependence. In the end the answer has to be, “yes, we can”.


