Tottenham have spent £1 billion less than their peers in the last decade, and this summer hardly changes that

Spurs may have splashed the cash this transfer window – but they have barely made a dent in their long-term spending deficit
Reaching into their pockets

It has been commonly understood that Tottenham have spent a great deal of money on transfers this window, much to the consternation of rival fans and Real Football Men™. After all, the club has added headline players such as Tonali, Fernandes, Van Hecke and now Savinho and Marmoush. And, after an inevitable opening day defeat at Brentford, trolls are asking if this supposedly ‘astronomical outlay’ will have any benefits.

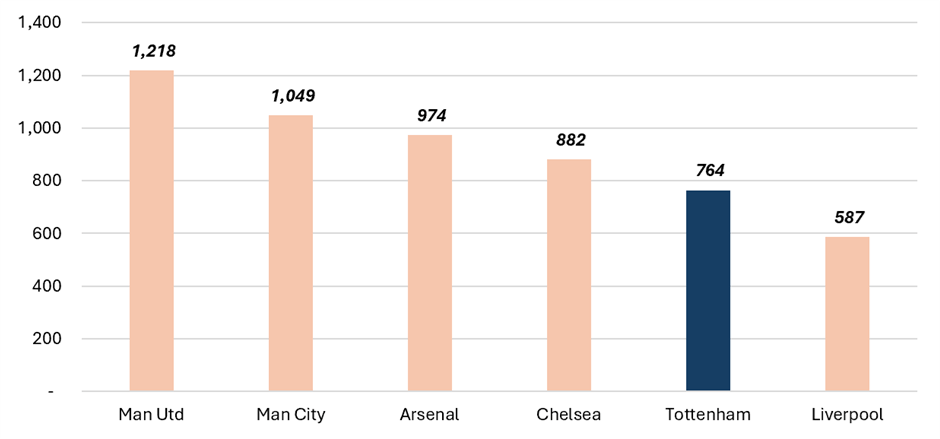
Furthermore, much of the media such as Simon Jordan continue to claim that Tottenham have “always spent big”, making this summer’s splurge seem even more egregious. The ‘net spend’ figures which are frequently bandied about seem to support this – the Spurs figure of £728m compares comfortably with the average of £894m averaged by the other five clubs.

Big Six ‘net spend’ since 2015 – 2025
Source: Transfermarkt

The reality though, is that Tottenham even now are still trying to make up for the underspend of the last decade or more. To understand exactly how much – and to gauge how much more reasonably needs to be spent, we need to peel back the layers of the figures. For these, I will stick to just the four clubs that are run properly: Arsenal, Liverpool and Man Utd as well as Tottenham (Man City and Chelsea have an entirely different business model and financial base, rendering comparisons pointless).

There are three methodological concepts needed to establish a good comparison between these clubs and I will go through each of them step by step.

Gross spend, not net spend

First, let us deal with the frequently cited concept of ‘net spend’. The reason this idea comes up is that it reflects the financial model used in computer games like Football Manager (or, if you are older, Championship Manager). In this, player purchases and sales are hard numbers coming out of a bank account, the same way that you might spend your pocket money.

However, this is not how football transfers work from a financial perspective: fees are deferred over a period of months and even years; much of it is shuffled off into working capital rather than coming out of cash (which can be funded by debt facilities); and it actually excludes cash costs such as agent fees and signing bonuses which can be substantial. More importantly, net spend is netted off against player sales, which are an entirely different business requiring different skills.

‘Net spend’ (like real GDP) is a terrible metric which has taken over as a short hand for investment. Instead, a club’s ambitions in the transfer market are really to be measured by its outgoings only (‘gross spend’) since it has far less agency over its incomings. Yes, clubs wait to offload players before signing others – but this is mainly a question of managing salaries, less about transfer fees.

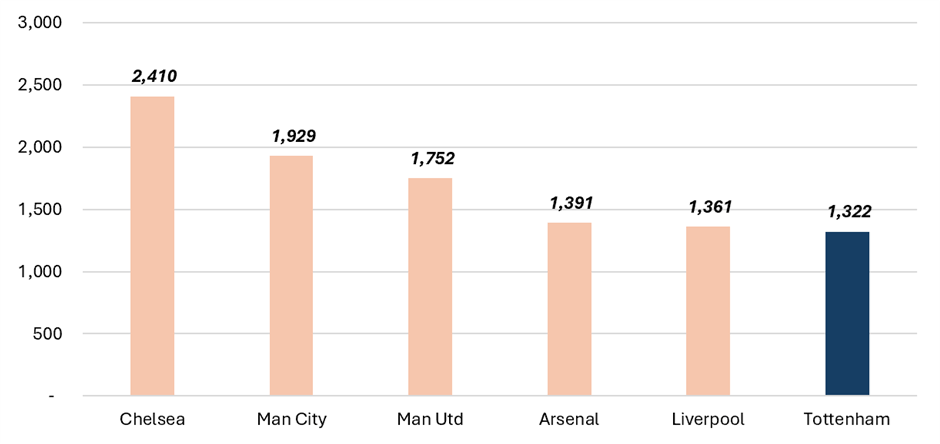
Big Six gross spend since 2015-2025
Source: Transfermarkt

Judged just on this measure, Tottenham are more clearly at the back of the pack, albeit not far behind Arsenal and Liverpool. But this is only the start of the story.

‘Big player’ spend, not overall spend

Secondly, not all player signings are the same. While from a financial perspective, a £50m player has ‘cost’ almost twice as much as two £30m players, this is not the footballing reality. Most fans will understand that the £50m player will be far more likely to important than the two £30m players combined, at least in the near term. The market suggests that they are better, they are more likely to be going straight into the first team, and they are also likely to be paid much more. Player value to the team increases exponentially as fees go up, so one simple way of looking at it is to square the transfer fee to calculate relative value: the square of two £30m is about 72% of the value of the square of one £50m player. We are into the realms of pure vibes here, but most observers would feel that this is about right. This quadratic application, re-based to a £100m transfer fee, might look like this:

The likely ‘true value’ of transfer fees
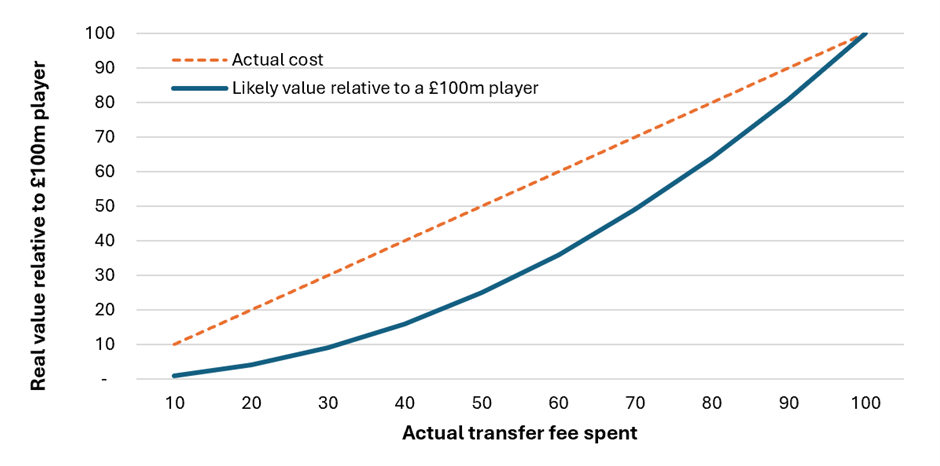
Notes: illustrative value curve assuming that £100m transfer fee = 1, ie that you get what you pay for, and therefore all other priced players are calculated relative to that – however one could choose any starting number

Therefore looking at spending on all players is less important than looking at spending on ‘big’, needle-moving players. One can debate what that cut-off means, but a reasonable rule of thumb is that players commanding fees of £50m or more, are generally the ones expected to play immediately and improve the first team, not just the squad. Additionally, the ‘big player’ threshold is a useful if imperfect proxy for how much a club is paying them, too.

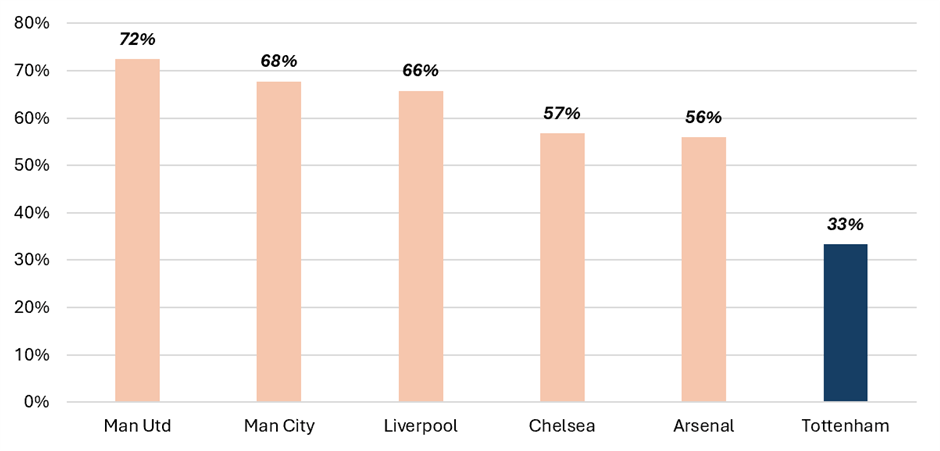
Percentage of gross spend used on transfer fees of £50m or more, 2015-2025
Source: Transfermarkt

The problem is clear: while Tottenham have spent a fair amount of money on transfers, its spending on ‘big players’ has been severely lacking. Instead Spurs have brought in dozens of at best squad-level players (and many probably not even that). Of all the Big Six teams, Tottenham’s portion of £50m is the most off-kilter, showing a real problem of ambition.

Today’s money

Next is the matter of football inflation, which I have dealt with previously. If we look back at, say, a decade of spending by Tottenham, we cannot treat every year the same since player prices have gone up. Tottenham did up their spending in recent years, but by then the money did not mean the same. Xavi Simons cost £52m in the summer of 2025, but the same amount spent on Aymeric Laporte by Man City in 2017 was clearly a lot more in real terms. In order to compare apples to apples, we therefore need to adjust fees for inflation.

Taking into account the £50m number as the needle-moving transfer fee, and looking back, this number reduces over the course of the last decade such as £50m in 2026 is about £41m in 2021 and £36m in 2016. Therefore, to compare real spending, we have to look at ‘big players’ in today’s money.

What £50m looked like in money of the day, since 1992
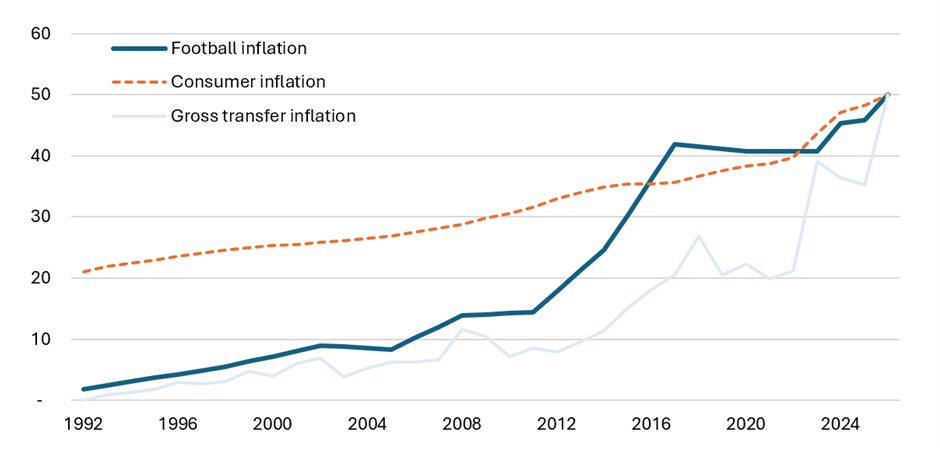
Notes: Football inflation calculated based on value of TV rights as per previous blog. For completeness, the implied inflation based on total Premier League actual gross spend annually since 1992 is also included, which has a 0.92 correlation with TV rights inflation but is more volatile and I feel less indicative of club management forward views affecting player prices. CPI from ONS.

Tottenham’s spending deficit

Until this summer, then, and even with the wallet being unleashed a little under Levy’s last window in charge, Tottenham over the last decade has underspent the rest of the Big Six by some £850m on average. To even catch up with the nearest spending rival, Arsenal, Spurs needed to spend more than £400m; but to catch up to, say, Manchester City, they needed not much over £1.1bn of new players. (I leave Chelsea out of this conversation for now simply because their business model under the current ownership is not the same.)

Big Six gross spend on players worth £50+ in today’s money 2015-2025 (£m)
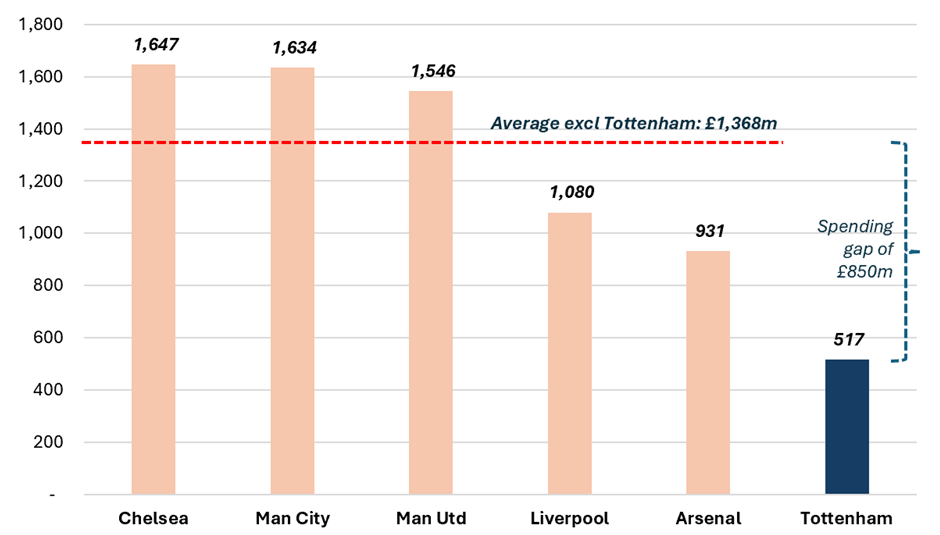
Source: Transfermarkt with inflation adjustments, full numbers below

To do this is tricky. First, it is impossible to spend so much in one transfer window at all, let alone do so without creating artificial price inflation because everyone knows you are doing so. Secondly, the figure shifts since the other teams are themselves spending more – Tottenham’s catch up spending needs to be net of new spending from the other clubs this summer. Lastly there is the softer elements, for instance how well Tottenham’s scouting and player assessment is compared to clubs which have been better run for so much longer, and whose infrastructure has been maturing for a decade. Tottenham struggle with both value and quality in trying to make up for lost time, as any club would under these circumstances.
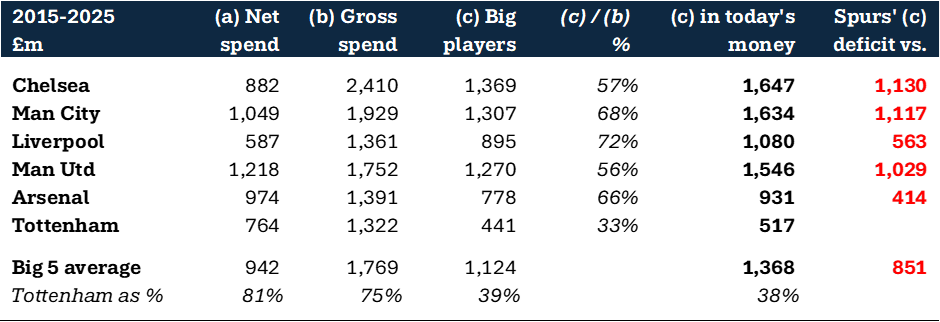
So yes, Tottenham are taking the requisite steps to make up for a lost decade of transfer activity. While we would all love to believe that success on the field could come from elsewhere, it is impossible to maintain a ‘Top Six’ status without spending being broadly in-line with the others. And while we can be very excited about the £300m+ invested this summer, this does not even put us top of the Big Six (Chelsea’s gross spend is almost £400m). There is still a long, long road ahead before we make up for the lost time relying on a few over-performers such as Kane and Son. Whether the Lewis family can maintain the appetite for this, is anybody’s guess.
Are transfer fees really more expensive? Not really.

While nominal spending is getting higher and higher, clubs are actually getting players cheaper than ever

The voice of sanity

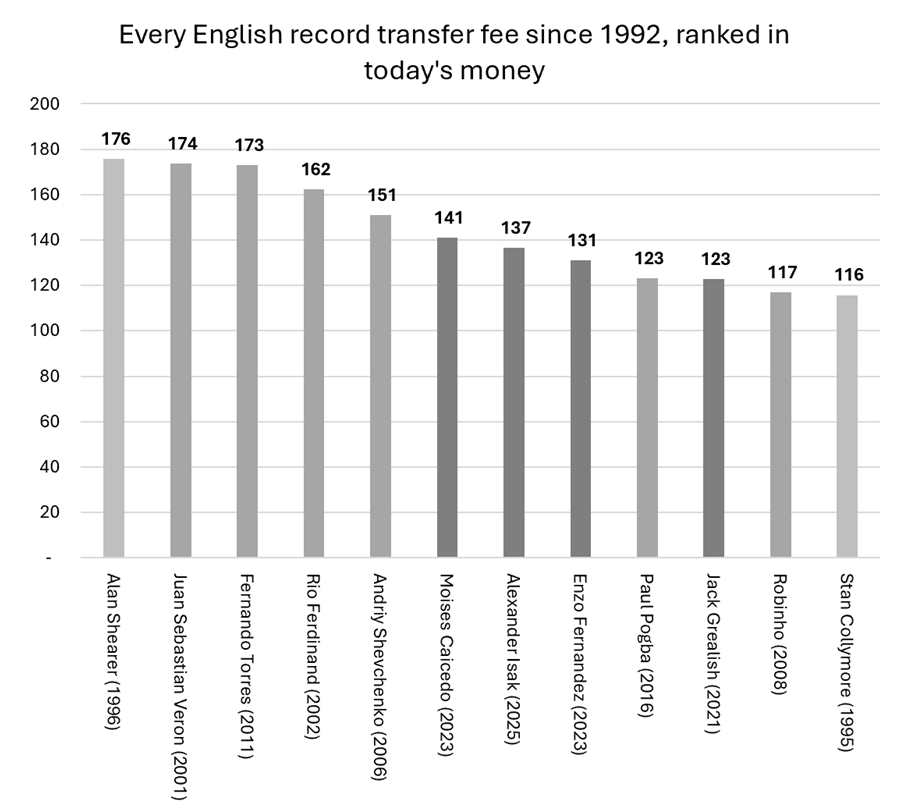
“Transfer fees have gone crazy”, according to those eternal barometers of sanity, TalkSport listeners, as they react to the transfers this summer of Morgan Rogers (£117m to Chelsea), Elliot Anderson (£116m to Man City) and even Sandro Tonali (up to £100m to Tottenham), not to mention Izak and Wirtz to Liverpool last summer. And in a sense, fees do seem to have picked up, given that the record was not broken for 7 seasons between the signing of Paul Pogba by Man Utd in 2016, and the arrival of Enzo Fernandez to Chelsea in 2023. Since then, transfer fees of over £100m have come thick and fast, leading to charges of inflation and insanity.

However people should remember that transfer fee inflation has been a fact of life since the beginning of football. Moreover, football inflation is not the same as CPI, ie the price of a pint of milk; rather it reflects the increasing amount of money coming into the game. To that end, I am updating my proprietary transfer fee inflator index, last written about almost a decade ago. As the data demonstrates, transfer fees today still pale in comparison to some of the biggest deals signed in the past.

There are a few other calculators floating around – for instance here, here and here – but none of them are satisfactory for me. For a start most do not seem to start earlier than 2000, which leaves out a lot of Premier League inflation. Secondly the Kieran Maguire index, which seems to produce reasonable results, rebases to 2019 cost of money and also there are no details that I can find on the calculation.

A recap on my methodology: since inflation is a function of supply and demand, I have based my inflator on the total Premier League TV rights money each year. The biggest change since my last post on this subject is the inclusion of overseas rights into the calculation, the value of which overtook UK domestic rights for the first time in 2023 (for those sad enough to be interested, I include a complete set of data in the appendices). Using the growth of the TV rights money as base line inflation, I then adjust transfer fees accordingly to reflect what their true cost was compared to TV income of the day. It is not perfect, but it is as good a proxy as I can think of to find a measure of ‘football inflation’ rather than normal consumer inflation.

Note: Shading reflects recency

The results speak for themselves. The most expensive transfers in Premier League history, have far outstripped recent deals in ‘today’s money’. Alan Shearer’s £15m transfer to Newcastle in 1995 is about £176m in modern terms, substantially higher than any of the sums being paid this year. Likewise the transfers of Veron in 2001 and most amusingly, Fernando Torres in 2011, which come in close behind. Incidentally Alan Shearer’s first transfer, from Southampton to Blackburn in 1992, falls just out of scope but probably comes in at around the £100m mark too. At these prices, Elliott Anderson or Tonali look cheap as chips by historical standards.

Furthermore, the reverse is also true. The £100m player of today is actually the £25m player of 2010, or the £10m player of 1998, the dates between which I suspect the formative views on transfer fees for many readers (and TalkSport listeners) was set. Certainly these historical numbers account for the reluctance of Daniel Levy or Arsène Wenger, and other ‘old men’ of football, to reject the pricing they saw in the market later on in their careers. They had become antiquated, with the only response that the market was “madness”.

How then, one might ask, do English clubs compare to their European counterparts? It is difficult to make an apples-to-apples comparison, since European TV money has not matched that of the Premier League for a couple of decades now; additionally their earning streams (particularly for Real Madrid and Barcelona) are not structured in the same way as English clubs. For the sake of a completeness, I have calculated what European transfer fees look like in today’s money based on English football inflation, in the appendix. However I do not believe this is an accurate way of looking at it.

A better way to understand what top European transfer fees have been is simply to compare transfer records in Europe vs England to the closest possible point in time. Using this method, we can see that in general, European clubs have committed to much higher headline prices than English clubs typically have – albeit these are driven by only a few clubs.

Note: Euro-sterling exchange rate using average of June-July in each relevant year; where possible, same year transfers have been used but where not, the English transfer used is one year preceding

Gianluigi Lentini’s move from Torino to Capello’s AC Milan in 1992, for instance, was truly a shock to the world in 1992, at almost £13m. It was 3.6 times the highest amount paid in England at that time, which was Alan Shearer’s transfer to Blackburn. Shearer’s next move, to Newcastle, was the closest England has had to a record, benchmarking close to Ronaldo’s record jump from Barcelona to Inter a year later. By the time the next headline was being made in England, with Veron’s purchase by Man Utd in 2002, Zidane was shuffling over to Real for close on twice the amount of money – indeed the Veron fee weighed in at less than that of Figo the year before (£38m), and Christian Vieri three years earlier (£32m).

Since that time, English clubs have actually spent conspicuously less at the top end of fees, even as they have powered to more overall spending. Nobody has come close to matching Neymar’s almost £200m move to PSG for instance, way back from the pre-Covid years. It seems unlikely they will do so any time soon. As a side note, the history of transfer records stands as a real testimony to the shifting fortunes of financial leadership in European football. In the 1990s, records were all set by Serie A; by the 2000s, this was now being set by the two Spanish giants; and in the years before Covid, PSG alone set records – not only the €222m for Neymar but also the €180m spent on Mbappe.

Note: exchange rate same as above; all transfer records have been included

In summary, while headline numbers continue to increase, in the context of club TV money the transfer fees of today are actually quite modest. £100m is the new normal for key players and this is less than was paid for many stars in the last three decades – fees are higher but they aren’t more expensive. English clubs have still never hit the astronomical heights that European counterparts have, either. So lament crazy prices by all means – but we have not really seen anything crazy, unless you want to make the case that Elliot Anderson is not as good a midfielder as Juan Sebastian Veron.

Appendices

1. Comprehensive transfer fee inflation model

Note: multiple and discount factor are derived from each new TV deal, announced in nominal terms, interpolated between the relevant years; Premier League domestic TV money peaked with the 2017-2020 deal, but still grew factoring in foreign rights. To use the table, take any historical transfer fee and its year, and multiply it in order to see the price in today’s money. Or in reverse, take a transfer fee of today, to see what its equivalent number was back when you were young.

2. Evolution of the European transfer record since 1992 (nominal top, re-based to Premier League inflation bottom)

Spain leads football innovation off the field, not just on it

Given the dominance of Real Madrid and Barcelona on La Liga, and the importance of men like Florentino Perez in European football discourse, the outside observer would be forgiven for overlooking the role of the governing bodies. After all, surely the biggest clubs – which vastly overshadow their domestic peers in a way that does not happen in the Premier League – call the shots?

But surprisingly, the Spanish football federation has not only frequently come out on top against their biggest club members, but has also been a historical pioneer in football governance in a way which has set the agenda across the continent.

Transfer windows

In 1995, La Liga instituted the first modern restrictions on player trading, allowing changes of club only during a long summer break and a shorter winter slot. Strange to think, that across Europe until then, all major leagues allowed unlimited transfers until each of their deadline days – end of January for Italy, February in Germany and France and absurdly the 31 March in England, mere weeks before the season ended. At the time, transfer windows were designed to protect smaller clubs by not allowing Real or Barca to take their rivals’ best players mid-campaign, and Spain even prevented mid-season moves if a player had already played 5 matches for their club. FIFA then went on to adopt this system wholesale, bringing cross-border alignment to all leagues by 2002 to the system we know today.

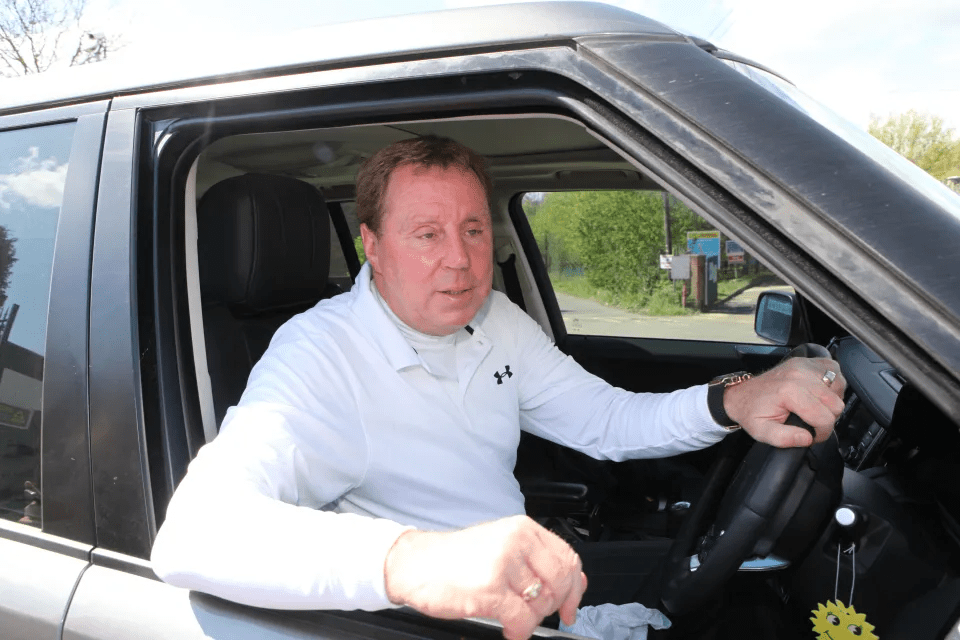
If no Spain, then no Harry Redknapp hanging out of his car window on transfer deadline days

Buyout clauses

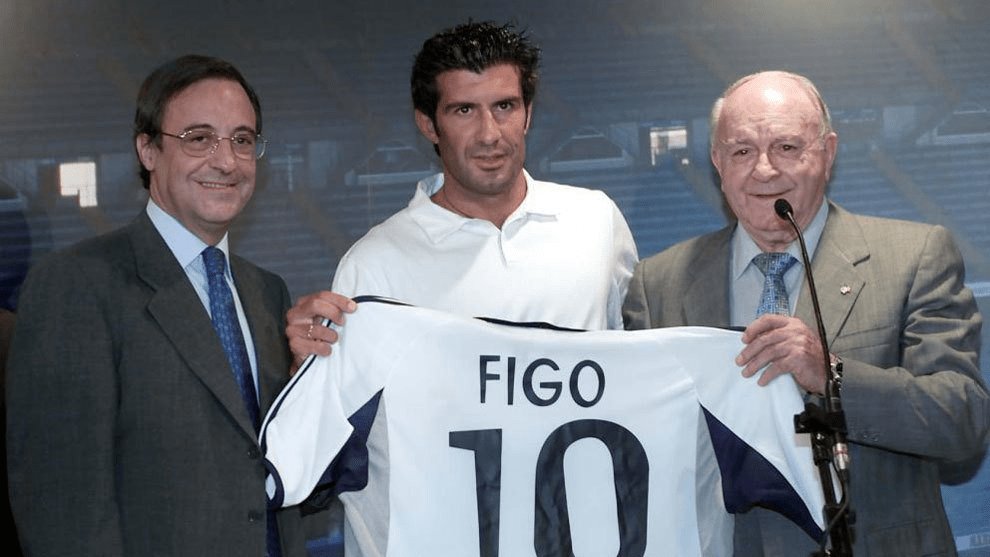
By the time of the Bosman ruling in 1995, Spain already had a system of buyout clauses described by World Soccer magazine, amongst others, as “positively futuristic”. In fact though, Spain had laid the groundwork for this a decade earlier when they actually had their own version of Bosman, leading to the Royal Decree 1006 which freed players to break contracts with their clubs. Clubs in turn responded by introducing the buyout clause – the difference with today being that the buying club actually gave the transfer value to the players themselves, who in turn paid their employer out and became a free agent. The most (in)famous example of this in action was Figo’s transfer from Barcelona to Real Madrid in 2000 for an astronomical €61m. Since that time, clubs around Europe began to normalise such clauses such that they are now commonplace.

Figo celebrating a victory for players’ rights

Image rights

In response to a change in the taxation rules in 1996, Spanish clubs began to split player compensation into two parts: salary and the use of image rights. This was revolutionary in two ways: first, it helped create a new world of tax avoidance which spread to most other leagues; secondly, it focused marketing attention on the image rights portion of football. Marketing agencies began to specialise in this segment which in turn changed the way the advertising industry used football. Image rights became a major political issue under Florentino Perez’s first Galacticos stint, but by then the Premier League and others had already taken up the baton. The reductio ad absurdum of this arrived through incidents such as Paulo Dybala’s transfer to England falling through in 2019 due to his image rights being sold and owned to third parties. At a club level, Barcelona’s rescue package in 2023, where they sold 25% of their future TV rights, is in some ways a continuation of this.

Salary caps

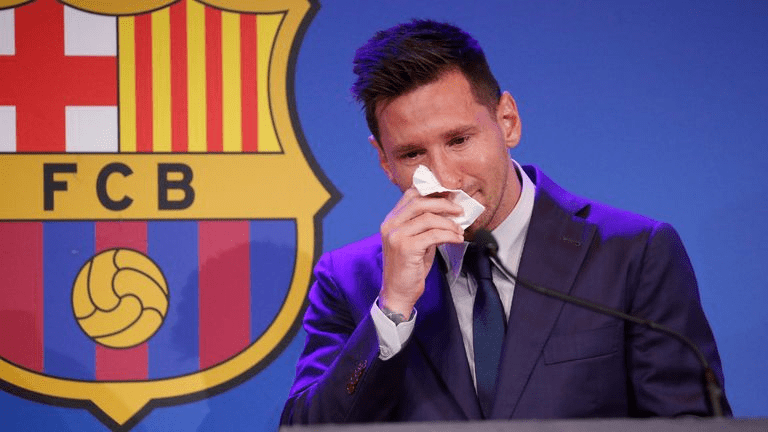
Before the coming of FFP in Europe, and then PSR and now SCR in England, Spain already developed a (seemingly quite heavy-handed) scheme for cost controls. Taking inspiration from US sports franchising, La Liga implemented a total squad salary cap from 2013 onwards, after several years where smaller clubs had come a cropper in the 2000s trying to chase down Real Madrid’s Galactico model. Many of them, moreover, were incurring ever greater debts to still buy players, while owing money on transfers and even wages to the current squad. In order to protect socio-owned clubs from themselves, La Liga actively calculated budgets and prevented new signings from being registered, a personal project from autocratic president Javier Tebas. The most high profile outcome of this was Barcelona’s inability to re-sign Lionel Messi – who was actually still at the club – on to a new contract in the summer of 2021 and hence pushing him out to PSG. Certainly not a case of the big clubs holding the system to ransom.

Messi lamenting the financial austerity only La Liga understood

Neutral venue matches

To be fair, in this area the Premier League did technically start earlier through its “39th Week” proposal in 2008, where the idea was to create an entire new round of fixtures to be played in various venues worldwide. However they backed down on it fairly quickly, where ten years later in 2018 Tebas (yes, it be he again) not only signed a new sports rights deal with Relevant Sports but went as far as to organise the Girona vs Barcelona fixture in Miami, scheduled for January 2019. While both clubs agreed to it, pressure from RFEF, UEFA and FIFA caused Tebas to back down – only for Relevant Sports to bring the lawsuits which forced UEFA itself to finally capitulate in 2025. Matches abroad are now permissible, all thanks to Spain.

Not only that, but Spain has been proactive in wanting to host others. The best example was Spain jumping at the chance to own the 2018 Libertadores Cup replay in Madrid between Boca Juniors and River Plate, after violence prevented the original fixture. However even further back, Spain offered to host everyone from Yugoslavian refugees Red Star Belgrade during their civil war, through to a number of Champions League matches during the height of Covid (not the final mini tournament, but several quarter-finals when logistics were much less sure).

Creation of a breakaway big money league

The most historical example of Spanish innovation is the creation of a more commercially orientated league setup, in anticpation of forthcoming revenues such as television rights. Spanish clubs broke away from the RFEF to form La Liga all the way back in 1984, a decade earlier than the Premier League. While in some respects, this act was as reminiscent of the Football League creation in 1888 as anything else, the similarities with more recent examples is the focus on commercialisation (the FA / Football League split was a contest over professionalisation vs amateurism as much as anything). La Liga was followed not only by the Premier League in 1992, but also the Bundesliga (2001), Serie A (2010) and the Ligue 1 (2022).

A side spur of this is the whole Superleague question. La Liga and the RFEF of course vociferously fought the idea of the Superleague, but ironically the culture of La Liga is what first set Real Madrid and Barcelona off on that direction alongside Juventus. And strange though it sounds to English or German ears, the idea of the Superleague is nowhere near as unpopular in Spain as it has been elsewhere, because the long-term culture to try new things has been cultivated over decades.

Championing employees and fans

*******

There are numerous reasons why Spain has always been so innovative in football governance. Some of this is deeplying in the legal and corporate culture of the country, including the focus on labour law post the Franco regime and the relatively litigious nature of the economy. Some of it has been driven by individuals such as Tebas or Perez. Above all though, Spanish football has always kept a weary eye on its place in the competitive landscape, particularly with regards Italy in the 1990s and then England since the 2000s. The authorites recognise the marketing strength of the big clubs, but also know that the whole product has to be sustainable in order to leverage that reach.

UEFA has headed off the Superleague for now, but the instincts which that proposal embodied – the innovative, the commercial, the litigious – had its roots mainly in Spain. And while the Premier League leads in revenues and sponsorship deals, it seems very likely that the next wave of innovations around governance will come once again from Spain. Ex Hispania semper aliquid novi, as Pliny might have said.

Remember blockchain? AI will bring it back into the limelight

AI may finally give blockchain its clear commercial case, by bringing physics into the digital world

Neon blockchain network linking secure data cubes and verified content

In the face of AI’s popularity with investors, blockchain and its uglier cousin crypto seem like yesterday’s news. Yes, a lot of fortunes were made and they are permanent, but attention and capital have moved on to the latest idea that threatens to change ‘everything’. Where crypto promised to overhaul finance and kill central banks, AI is positioned as the white collar job destroyer – although amusingly nobody really knows which way it will go. The Financial Times, lover of all things based on the 1990s consensus, famously offered this insight – and only partly in jest:

Meanwhile blockchain, while somewhat understood in digital circles, has continued to look for its true ‘moment’ where the use-case becomes compelling and, more importantly, monetizable. What we know is that true digitalisation has, even today, yet to arrive onto the financial services scene. While banks can slap apps on to their front end for customer interface, in truth the vast majority of financial services are still very much analogue – often even paper based – with digital as a gloss on top. In that sense, there is still huge headroom for full real digitalisation to be implemented, but it seems like a boring B2B process which will generate earnings but probably for the Accentures of this world.

But if we take a step back, what does blockchain really achieve which is useful every day? More than anything, the thing to remember is that blockchain brings the laws of physics online. This is an extremely simple point to digest but an equally difficult concept to appreciate the magnitude of. Blockchain means finally that irreplicability, and finity, are possible with digital assets in a way that for the first three decades of the internet’s existence they were not. And this is not about creating NFTs for art, though that is one niche application; it is about mass, common items that we use everyday.

Put simply, consider the real world: if Toyota produces 100,000 examples of a certain car, it is a mass produced item. Almost all the 100,000 vehicles are basically the same. Yet from an atomical perspective, they are each different, and the 100,001st car that Toyota produces requires yet more mass and energy that the first 100,000 did not use (remember, E = mc²). Moreover, while the 100,000 that Toyota produces are all ‘original’, an imitator which produces a similar car cannot produce it exactly, however hard they try. Physics prohibits it since they will use different machinery in a different geography using different materials. Toyota ‘owns’ those cars they produced, at source.

However in the digital world, there are no such constraints. If you receive a pdf file, even with a password protection, you can still replicate it as many times as you want. Yes, your ability to send these to other people costs power and bandwidth resources, but the fact is that the 100,001st copy of this pdf effectively does not differ from the 100,000th, or even the 1st. They can be exact replicas because there is not ‘atomic level’ online. Blockchain however, changes this. The purpose of the proof of work concept is that you now do know if you have one of the original 100,000 copies of a pdf, not the 100,001st pirated copy; and this in turn allows you to trade or sell it, something impossible before.

Now how does this all lead to AI? If my social media is to be judged, AI will fast take over much media content creation including pictures and videos (indeed we should probably coin new terms for these AI-generated outputs). My Instagram feed, for instance, is probably getting close to being 50% AI-generated and the comments sections enjoy calling them out. For the moment, there is still a novelty value in AI imaging and content. AI usage today still represents a clear cost benefit which can be applied across the industry, helping make content more quickly and cheaply. Furthermore, AI output quality still has room to improve (quite a lot of room, frankly).

Yet this improvement is the very reason blockchain becomes relevant again. I am certain that as AI starts to permeate the landscape and especially when it begins to seem indistinguishable from real life, consumers will start to finally want to pay a premium – for the real thing. Real actors in real studios, or God forbid out in the real world, will have its own desirability, for all their imperfections. While AI is driving content towards being almost free, its commoditisation means that the other end of the spectrum is where the monetisation case will be.

Nowhere is this more easily understood than in porn, which famously occupied as much as 30% of total internet usage. This is an industry that is being quickly penetrated by AI content, as both traditional studios and OnlyFans creators use artificial ways to supplement production in order to increase regularity and volume of new output. Intuitively, this will be one of the first areas where discerning consumers will desire – and start paying for – content that in some way is stamped as ‘authentic’. While everyday porn will become increasingly free, authentic human porn will start to command higher and higher prices – indeed the rise of OF is itself already a testament to the demand for this.

Back to blockchain, the best and from what I can see only way for this authentication to occur, is through ‘proof of work’ to be input at source. This means that at the point of production, the raw content is stamped as real life, and whatever edits and production are done afterwards, the veracity of the original filming is kept. It also means that next generation content creation tools such as video recording cameras and equipment, will have blockchain encoded within the machine themselves, going on-chain at the ‘point of click’ – the most logical point of verification. The same of course will be true for audio equipment and music generation and so on.

In this sense, beyond the boring world of financial instruments (crypto exchanges such as Binance now already offer direct trading of conventional securities such as equities and ETFs), blockchain will become the bedrock of how to monetise ‘true content’. So while AI is taking the headlines and absorbing capital and investment bandwidth today, blockchain should find a second wind in terms of its direct relevance to our lives. Physics is back.